
Share:

Why Real-Time Metal Pricing Intelligence Matters in Volatile Markets
Ever wonder why keeping tabs on the non-ferrous metals industry feels so unpredictable lately? As essential backbones for everything from automotive manufacturing and renewable energy grids to consumer electronics and aerospace, non-ferrous metals like copper, aluminum, zinc, and lithium are constantly shaped by fast-moving supply disruptions, shifting regional premiums, and volatile energy costs.
That is where comprehensive intelligence platforms like Grand View Signal step in, giving procurement teams and market analysts real-time visibility into non-ferrous metal pricing, feedstock bottlenecks, and global supply chain shifts. In this post, we will walk through the latest monthly market updates across key non-ferrous, specialty, and precious metals so you can make smarter, stress-free buying decisions.
1. Copper: Why Feedstock Bottlenecks Are Stealing the Spotlight
If you have been keeping an eye on copper lately, you might have noticed that the real story is not just about what end consumers are buying, the real drama is happening much earlier in the chain.
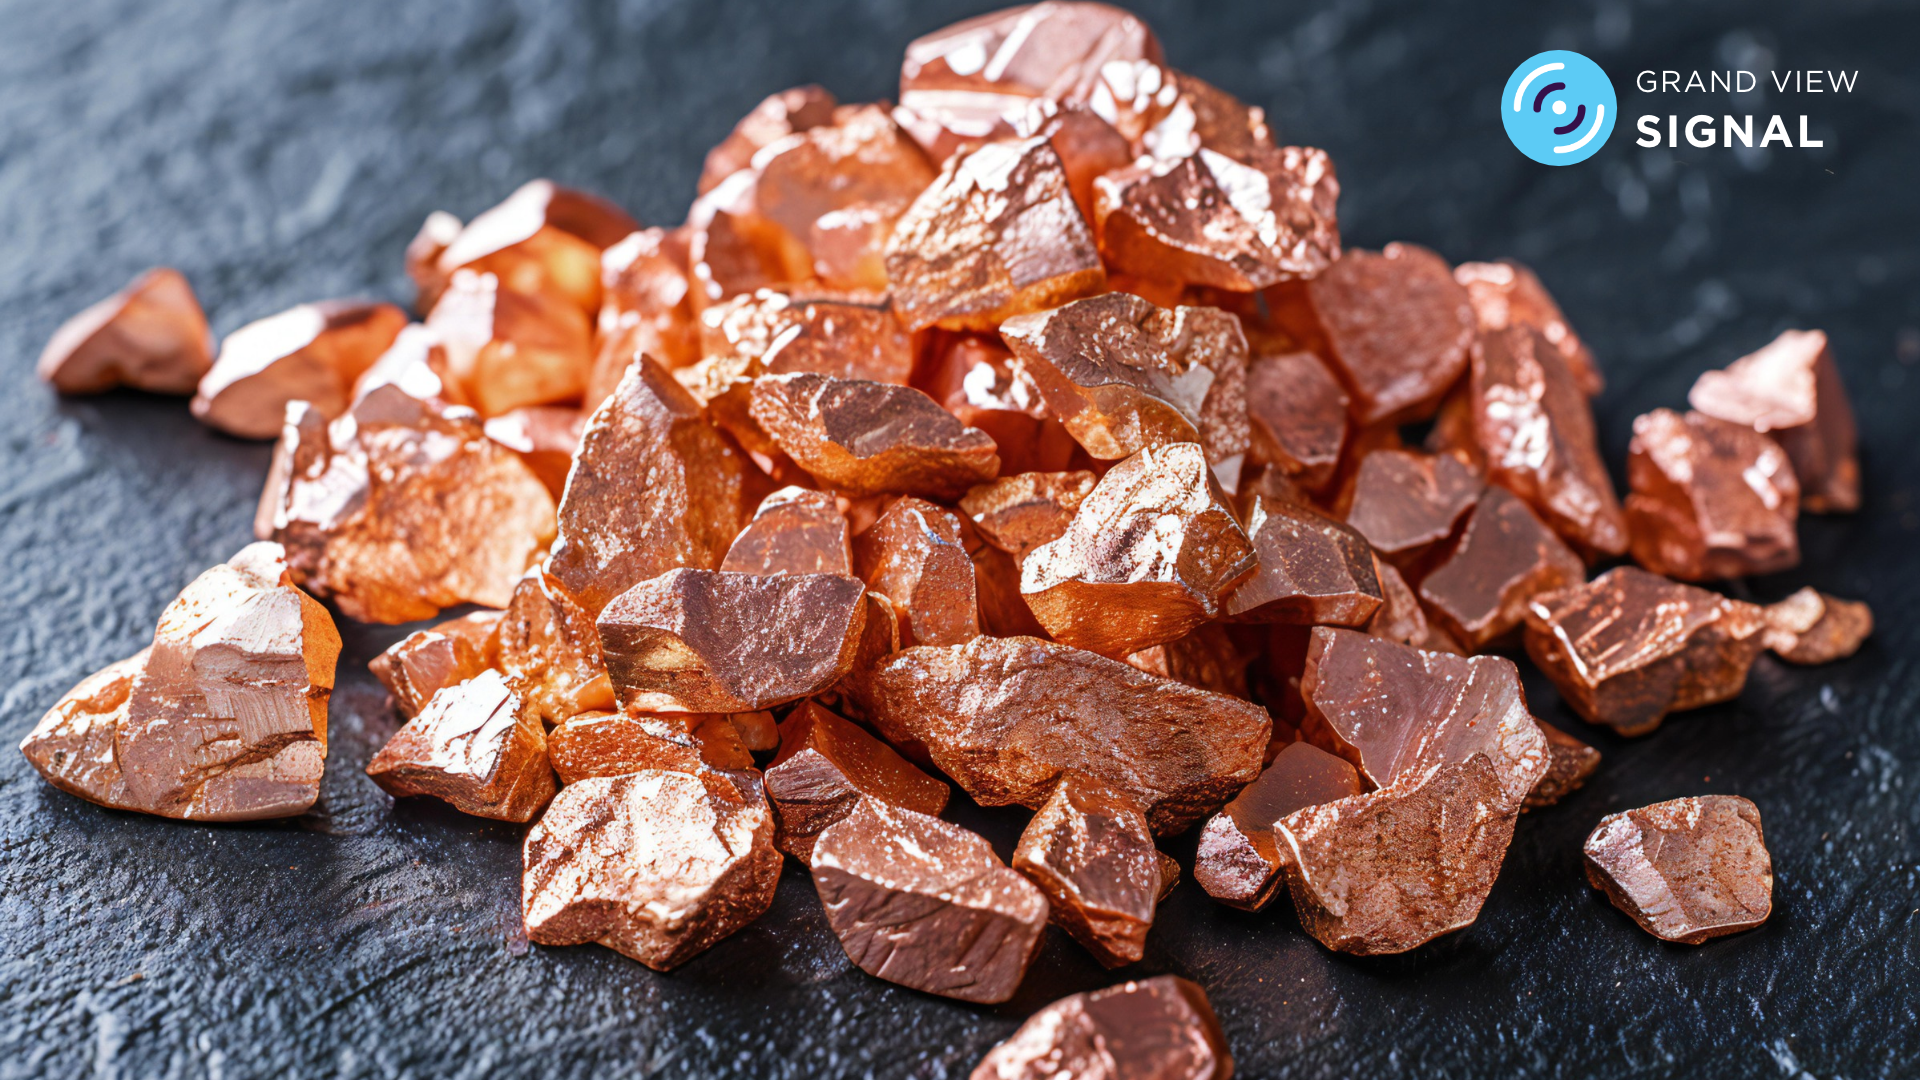
Smelters around the globe have been running into a persistent double whammy: a genuine shortage of copper concentrate mixed with tighter scrap availability. On top of that, sulfuric acid, a classic smelting byproduct that usually brings in a nice extra revenue stream, has been yielding lower returns. When profits on your byproducts drop, there is much less reason to keep output high at all costs.
So, what does this mean if you buy refined copper?
- Refinery Breaks: Major Chinese refiners started planning maintenance for October and November, which put the timing of future refined deliveries front and center.
- The Stocking Dilemma: Even though physical supply feels tight, high outright copper prices have made downstream buyers pretty cautious about holding extra stock.
- The Big Question: Buyers are left wondering how fast these raw material bottlenecks will turn into actual shortages of refined metal in their local markets.
Schedule a free demo of Grand View Signal to get a real-time preview of price fluctuations in the non-ferrous metals sector
2. Aluminum and Zinc: A Tale of Two Very Different Markets
It is easy to look at low warehouse stock and assume a metal is scarce, but that does not tell the whole story. You really have to look at current production alongside stored inventory, and aluminum and zinc show just how different those pictures can be.
- Aluminum: Working Through the Recovery Phase
Facilities in the Gulf region have been bouncing back from earlier disruptions. For instance, recently, EGA restarted 50% of its Al Taweelah aluminum smelter. However, rebuilding supply chains and getting stock back onto exchanges takes time. As a buyer, you still need to pay close attention to where your material is coming from, the shipping routes, and regional premiums when comparing quotes.
- Zinc: Real Scarcity at the Mines
Zinc is dealing with a very different puzzle. Global mine production dropped in the first half of the year, leaving smelters competing hard for concentrate while accessible exchange stocks stayed low. Throw in higher energy costs squeezing Western refining margins, and things stay tight.
While aluminum buyers are mostly watching the speed of restored shipments, zinc buyers need to keep an eye on fresh mine supply and smelter profitability.
Get detailed driver impact analysis on non-ferrous metals prices. Request Free Access to Grand View Signal
3. Lithium and Battery Metals: Balancing Seasonal Rush Against Incoming Supply
After taking a steep nose-dive earlier in the year, lithium carbonate saw a solid rebound in September. But if you talk to downstream battery buyers, they aren't quick to celebrate, most are hesitant to call a futures recovery a true physical shortage just yet.
Here is what is actually going on under the hood:
- Record Ore Deliveries: China brought in record imports of spodumene ore in August. As that material works its way through processing plants, converter output should start climbing.
- Peak Season Boost: Fresh orders from the battery and energy storage sectors gave prices a nice lift during their usual seasonal peak.
- The Waiting Game: You can't turn raw ore into usable battery material overnight. The ore has to be processed, tested, delivered, and absorbed into existing inventory before buyers feel real relief.
Meanwhile, cobalt has been charting its own path with export quotas in the Democratic Republic of Congo cutting down raw material supply before it ever reaches refiners. And over in specialized tech, lithium metal battery grade remains bound by its own strict specifications and custom qualification steps.
Get historical, current, and forecast non-ferrous metals price assessments. Request Free Access to Grand View Signal
4. Specialty Metals and Alloys: It All Comes Down to Specific Products
Share:
More in Business
View categoryCSIR NET Syllabus 2026: Subject-Wise Guide and Preparation Strategy
Explore the CSIR NET Syllabus 2026 with subject-wise preparation guidance for Chemical Science, Physical Science, Life Science, Mathematical Science, and Earth Science. Learn study planning, revision techniques, previous-year question practice, and mock-test strategies with IFAS Online.
Interior Designer In Delhi NCR | Complete Home Solutions
Searching for an Interior Designer In Delhi NCR who offers complete solutions under one roof? SKF Contractor designs homes, offices and shops across cities like Delhi, Noida, Gurgaon, Ghaziabad and Faridabad with a focus on comfort and style.
READ ARTICLE