Share:
How to Scale Institutional RWA Tokenization Across Multiple Blockchains Without Fragmenting Asset Liquidity
Learn how institutions can scale RWA tokenization across multiple blockchains while preserving compliance, interoperability, and unified asset liquidity.
Institutional real-world asset (RWA) tokenization is moving beyond isolated blockchain pilots. Tokenized funds, Treasury products, private credit, bonds, equities, and other financial assets are increasingly being deployed across Ethereum, Layer 2 networks, Solana, Avalanche, Polygon, BNB Chain, and purpose-built institutional networks. Coinbase Research describes a clear shift toward a more multi-chain tokenization landscape, even as Ethereum and its Layer 2 ecosystem remain important settlement environments.
But deploying the same asset across several blockchains creates a problem that faster transactions cannot solve: liquidity fragmentation.
If an institutional fund is represented by separate token contracts on Ethereum, Polygon, and another network, investors may see three markets instead of one. Liquidity becomes divided, prices can diverge, compliance data can become inconsistent, and market makers have to manage several fragmented pools.
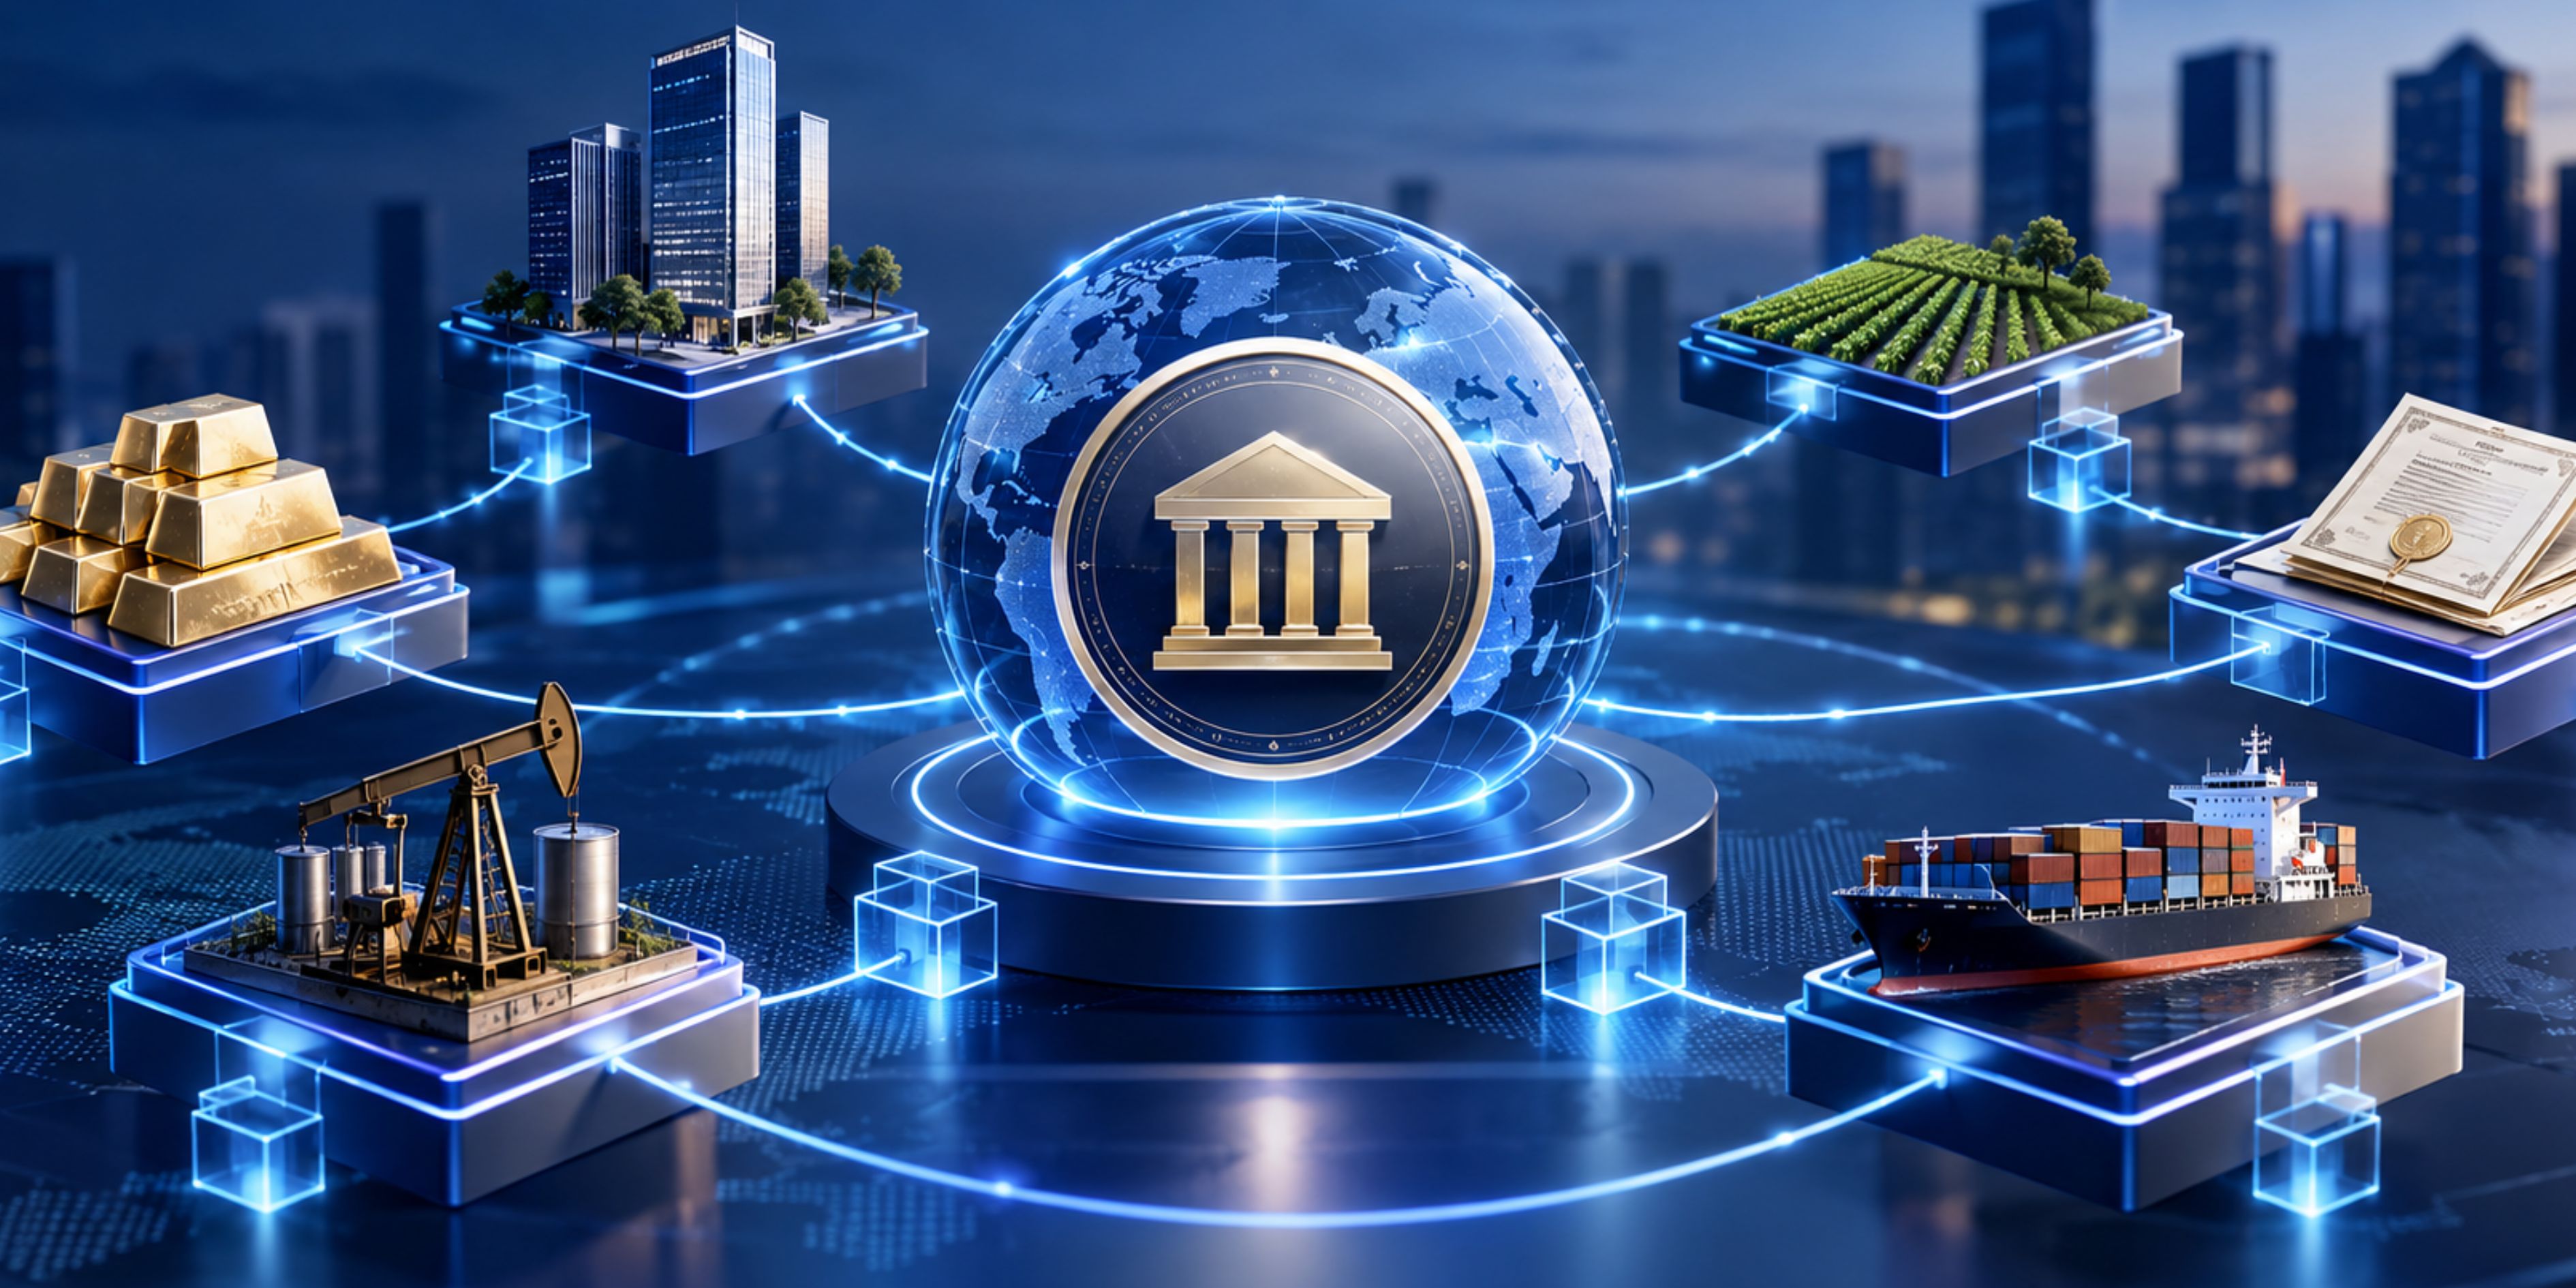
For institutions, therefore, the objective should not be simply to "go multichain." The objective should be to create a multichain asset with a unified economic, legal, compliance, and liquidity state.
This is where modern Real-World Asset Tokenization Services need to evolve.
Why Multichain RWA Tokenization Creates a Liquidity Problem
Traditional financial markets generally maintain a canonical record of ownership and obligations. Blockchain-based markets introduce multiple independent ledgers.
Consider a $100 million tokenized private-credit fund. Suppose $40 million is issued on Ethereum, $35 million on Polygon, and $25 million on another institutional network.
The underlying fund is still one economic asset, but its digital representation is now distributed across three environments.
This can create:
- Separate liquidity pools
- Different investor registries
- Inconsistent transfer restrictions
- Duplicated compliance checks
- Cross-chain pricing discrepancies
- Fragmented market-maker inventory
- Additional bridge and settlement risks
The problem becomes particularly serious for regulated assets. A compliance rule such as an investor cap cannot simply be evaluated independently on each blockchain if investors can hold the same economic interest across multiple networks.
Recent institutional infrastructure work is increasingly addressing exactly this problem. The ERC-3643 ecosystem, for example, has highlighted the difficulty of enforcing cross-chain investor restrictions when each network sees only its own portion of an asset's ownership state.
Therefore, institutions need an architecture where blockchains act as execution and distribution environments rather than isolated sources of truth.
1. Establish One Canonical Asset Identity
The first requirement is a canonical identity for the underlying asset.
Instead of treating each chain's token as an independent asset, the infrastructure should maintain a unique asset identifier linked to:
- Legal ownership
- Asset documentation
- Custodian records
- Valuation
- Encumbrances
- Issuance quantity
- Investor eligibility
- Corporate actions
- Transfer restrictions
The blockchain representation can then reference this canonical identity.
This distinction matters because token bridging alone does not guarantee that the underlying asset state is synchronized. Moving a token from Ethereum to another chain only moves a representation. It does not automatically prove that ownership, valuation, collateral status, or compliance information remains consistent.
Orochi's analysis identifies cross-chain data fragmentation as a deeper scalability problem than token bridging itself. Its proposed model emphasizes a "write once, verify everywhere" approach in which the same verified asset state can be independently validated across multiple chains.
For institutional infrastructure, this means asset identity should be chain-agnostic.
2. Separate the Asset State From the Settlement Layer
A scalable architecture should separate three layers:
Asset layer:
The legal and economic identity of the underlying RWA.
Compliance and data layer:
KYC/AML status, eligibility, valuation, ownership, restrictions, and asset-state proofs.
Settlement layer:
The blockchain where a transaction actually executes.
This architecture allows an institution to add another blockchain without creating an entirely new asset.
For example, an issuer could initially distribute a tokenized Treasury fund on Ethereum. Later, it could make the same fund available through Polygon or another institutional network without creating an economically independent pool.
The settlement network changes. The underlying asset does not.
This approach aligns with the broader institutional movement toward interoperable ledgers rather than disconnected blockchain islands. The BIS has proposed a "unified ledger" concept in which tokenized assets and regulated forms of money can operate across interoperable networks while preserving legal and settlement integrity.
3. Use Compliance-Aware Token Standards
Multichain RWA infrastructure cannot treat compliance as an external dashboard.
For regulated securities, transfer eligibility may depend on jurisdiction, investor type, accreditation status, holding periods, sanctions screening, concentration limits, and other restrictions.
Standards such as ERC-3643 are increasingly relevant because compliance logic can become part of the token's transfer architecture rather than remaining entirely off-chain. Blocsys also highlights ERC-3643 as a standard designed for regulated RWA environments, alongside conventional ERC-20 implementations.
However, multichain deployments introduce another requirement: compliance state must be synchronized across networks.
If an investor reaches a holding limit on Ethereum, a second transaction on Polygon should not bypass that restriction.
A shared compliance state, interoperable identity framework, or verifiable cross-chain compliance layer can prevent this.
4. Move From Token Bridging to Cross-Chain Settlement
Traditional bridges are not necessarily the ideal foundation for institutional RWA markets.
Institutions may not want to continuously lock an asset on one chain and mint a wrapped representation on another. This can introduce additional smart-contract dependencies, custody assumptions, liquidity requirements, and operational risks.
A more sophisticated model is cross-chain messaging and delivery-versus-payment (DvP).
The goal is to allow:
Asset on Chain A + payment on Chain B → atomic settlement
without requiring the institution to permanently create fragmented liquidity pools.
A 2025 ERC-3643 initiative demonstrated cross-chain DvP between Polygon and Base, allowing regulated security tokens and cash-equivalent tokens to settle across separate networks without requiring counterparties to bridge the assets themselves.
This model is particularly relevant for institutional markets because the security and cash legs do not always need to exist on the same blockchain.
5. Keep Liquidity Unified, Not Merely the Token
A common mistake is assuming that making an asset available on five chains automatically creates five sources of liquidity.
It can actually do the opposite.
Suppose a $500 million tokenized fund has:
- $200M liquidity on Ethereum
- $100M on Polygon
- $80M on Solana
- $70M on Avalanche
- $50M on another network
The asset is multichain, but liquidity is fragmented.
Instead, the infrastructure should enable market makers, exchanges, custodians, and institutional investors to access a shared liquidity state.
This can involve:
- Cross-chain order routing
- Unified market data
- Shared investor eligibility
- Cross-chain settlement
- Liquidity aggregation
- Canonical pricing
- Atomic or near-atomic DvP
- Interoperable custody infrastructure
This distinction is becoming more important as tokenized asset markets grow. Stobox notes that tokenization value has expanded significantly while secondary-market activity remains much thinner, reinforcing the point that issuance alone does not create liquidity.
6. Make Valuation and Asset Data Verifiable
Liquidity depends on confidence in price.
A market maker is unlikely to provide deep liquidity for a tokenized private-credit portfolio if its NAV, collateral status, or underlying asset data is stale or difficult to verify.
Traditional oracle systems solve part of the problem by bringing external information on-chain, but institutional tokenization increasingly requires more than a periodic price feed.
The infrastructure should establish verifiable links between:
Source data → calculation → valuation → token state
This becomes especially important when the same asset exists across multiple chains.
Every network should be able to verify that it is using the same underlying valuation rather than independently consuming potentially inconsistent data.
Chainlink's tokenization framework similarly emphasizes the importance of connecting real-world data, blockchain infrastructure, and value transfer to create interoperable tokenized markets.
7. Design Liquidity Into the Legal Wrapper
Technical interoperability cannot compensate for weak legal structuring.
A token represents rights. Those rights must be clearly connected to the underlying asset, SPV, fund, debt instrument, or other legal structure.
The legal wrapper determines:
- What investors actually own
- Redemption rights
- Transfer restrictions
- Governance rights
- Bankruptcy treatment
- Jurisdiction
- Custody arrangements
- Corporate actions
Stobox's 2026 research makes this point directly: the legal wrapper and structuring model can have a greater impact on institutional liquidity than the token-minting mechanism itself.
Therefore, institutions should design legal, compliance, technical, and liquidity architecture together rather than selecting a blockchain first and solving legal structure afterward.
8. Connect Tokenized Assets to Institutional Trading Infrastructure
The final step is connecting tokenized assets to actual trading venues.
A tokenized asset has limited economic value if investors can only buy it at issuance and cannot efficiently transfer, trade, redeem, or use it as collateral afterward.
Institutional infrastructure should connect tokenized assets with:
- Regulated exchanges
- OTC desks
- Custodians
- Lending markets
- Collateral systems
- Settlement networks
- Payment rails
- Portfolio management systems
This is where crypto exchange development services can become an important component of an institutional RWA strategy. A compliant exchange infrastructure can provide order management, liquidity aggregation, custody connectivity, investor permissions, and secondary-market access while the underlying RWA infrastructure maintains the asset's legal and compliance state.
The direction of the market is already moving toward deeper integration between traditional market infrastructure and tokenized assets. DTCC's 2026 work on tokenized collateral focuses on multichain interoperability, collateral mobility, and production-scale infrastructure rather than isolated blockchain experiments.
A Practical Architecture for Multichain Institutional RWA
A scalable institutional architecture can therefore be structured as:
Real-world asset → Legal wrapper → Custodian → Canonical asset registry → Compliance/data layer → Tokenization layer → Interoperability layer → Multiple settlement chains → Liquidity venues
The key is that the asset registry, legal identity, compliance state, and economic representation remain coherent even when execution occurs across different blockchains.
This prevents every new blockchain from becoming a separate market.
How Debut Infotech Approaches Institutional RWA Infrastructure
For institutions evaluating Real-World Asset Tokenization Services, the focus should move beyond smart-contract deployment toward complete infrastructure architecture.
Debut Infotech can support institutional RWA initiatives by combining tokenization infrastructure with compliance-aware smart contracts, multichain interoperability, asset management workflows, secondary-market integration, and blockchain-based settlement.
The objective is not simply to put an asset on multiple blockchains. It is to create an architecture where multiple blockchains can access the same economic asset without creating disconnected liquidity silos.
Conclusion
Multichain RWA tokenization is likely to become a defining architecture for institutional digital assets. But simply deploying tokens on more networks does not solve the institutional liquidity problem.
The scalable model is based on five principles:
- One canonical identity for each underlying asset
- A shared and verifiable compliance/data state
- Interoperability between independent settlement networks
- Unified liquidity and cross-chain settlement
- Legal structures designed for transferable institutional rights
The industry's direction increasingly points toward interoperable networks, programmable settlement, tokenized collateral, and unified liquidity rather than isolated blockchain ecosystems. BIS, DTCC, and institutional tokenization initiatives are all exploring infrastructure that connects multiple ledgers and financial systems rather than creating another collection of disconnected digital markets.
The winners in institutional RWA tokenization will therefore not necessarily be the chains with the highest throughput. They will be the platforms capable of making one real-world asset behave like one coherent market across many blockchains.
Share:
More in Technology
View categoryWhat Is the Difference Between Code Review and Penetration Testing?
Learn the difference between code review and penetration testing, including how each finds security vulnerabilities and when businesses should use them.
READ ARTICLEBuilding Smarter and More Resilient Businesses in Saudi Arabia
Explore Azure OpenAI, agentic AI integration, and disaster recovery solutions in Saudi Arabia to improve business automation, innovation, security, and resilience.
READ ARTICLEiPhone Repair Myths Debunked, What Newport Residents Get Wrong
iPhone Repair UK specialises in iPhone and iPad repairs, offering expert screen, battery, charging port, camera, and water damage repairs with fast, reliable service and same-day repairs available.
READ ARTICLE